Stabilized CAGR, Q1 2016 – Q2 2026
| Metric | Whole company | Per stab. share |
|---|---|---|
| NOI | 1.9% | 1.5% |
| EBITDAre | 1.5% | 1.1% |
| FFO[5] | 7.7% | 7.3% |
| AFFO | 2.7% | 2.2% |

Definitions. NOI (Net Operating Income) = rental income less direct property operating expenses, including real estate taxes and insurance. EBITDAre = Earnings Before Interest, Taxes, Depreciation and Amortization for Real Estate (Nareit definition). FFO (Funds from Operations) = net income excluding real estate depreciation and gains or losses on property sales (Nareit definition). Normalized FFO (NFFO) = EQR's FFO excluding non-comparable items (impairments, pursuit-cost write-offs, debt extinguishment, non-operating gains, merger costs and similar). AFFO (Adjusted Funds from Operations, cre42 definition) = Normalized FFO less recurring capital expenditures. CFO (Cash Flow from Operations) = as-reported net cash provided by operating activities. TEV (Total Enterprise Value) = market capitalization plus total value of debt plus preferred shares and other debt-like obligations. CAGR = Compound Annual Growth Rate.
| Metric | Whole company | Per stab. share |
|---|---|---|
| NOI | 1.9% | 1.5% |
| EBITDAre | 1.5% | 1.1% |
| FFO[5] | 7.7% | 7.3% |
| AFFO | 2.7% | 2.2% |
| TTM | Q3 25 | Q4 25 | Q1 26 | Q2 26 | |
|---|---|---|---|---|---|
| AFFO / STAB MKT CAP | 5.3% | 5.5% | 5.6% | 6.1% | 5.2% |
| FFO / STAB MKT CAP | 5.8% | 6.5% | 6.2% | 6.0% | 5.9% |
| EBITDAre / STAB TEV | 5.4% | 5.9% | 5.6% | 5.4% | 5.5% |
| NOI / STAB TEV | 6.1% | 6.3% | 6.5% | 6.6% | 6.1% |
| 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | 2026 ann. | |
|---|---|---|---|---|---|---|---|---|---|---|---|
| NOI | $4.61 | $4.61 | $4.71 | $4.93 | $4.62 | $4.21 | $4.81 | $5.01 | $5.22 | $5.37 | $5.40 |
| EBITDAre | $4.45 | $4.29 | $4.32 | $4.51 | $4.30 | $3.78 | $4.34 | $4.53 | $4.59 | $4.79 | $4.65 |
| FFO | $3.05 | $3.21 | $3.17 | $3.42 | $3.27 | $3.00 | $3.54 | $3.77 | $3.80 | $3.97 | $3.78 |
| AFFO | $2.74 | $2.78 | $2.90 | $3.16 | $3.02 | $2.71 | $3.10 | $3.24 | $3.50 | $3.52 | $3.56 |
| CFO | $3.02 | $3.37 | $3.57 | $3.80 | $3.34 | $3.29 | $3.75 | $3.95 | $4.07 | $4.26 | $3.67 |
| 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | 2026 ann. | |
|---|---|---|---|---|---|---|---|---|---|---|---|
| NOI | -0.1% | 2.2% | 4.7% | -6.3% | -8.9% | 14.3% | 4.3% | 4.0% | 2.9% | 0.7% | |
| EBITDAre | -3.6% | 0.9% | 4.3% | -4.6% | -12.2% | 14.9% | 4.4% | 1.3% | 4.4% | -2.9% | |
| FFO | 5.2% | -1.3% | 8.0% | -4.5% | -8.2% | 18.2% | 6.3% | 0.8% | 4.6% | -4.7% | |
| AFFO | 1.4% | 4.4% | 9.0% | -4.5% | -10.1% | 14.3% | 4.7% | 8.0% | 0.6% | 1.0% | |
| CFO | 11.7% | 5.8% | 6.6% | -12.2% | -1.6% | 14.2% | 5.1% | 3.1% | 4.6% | -13.7% |
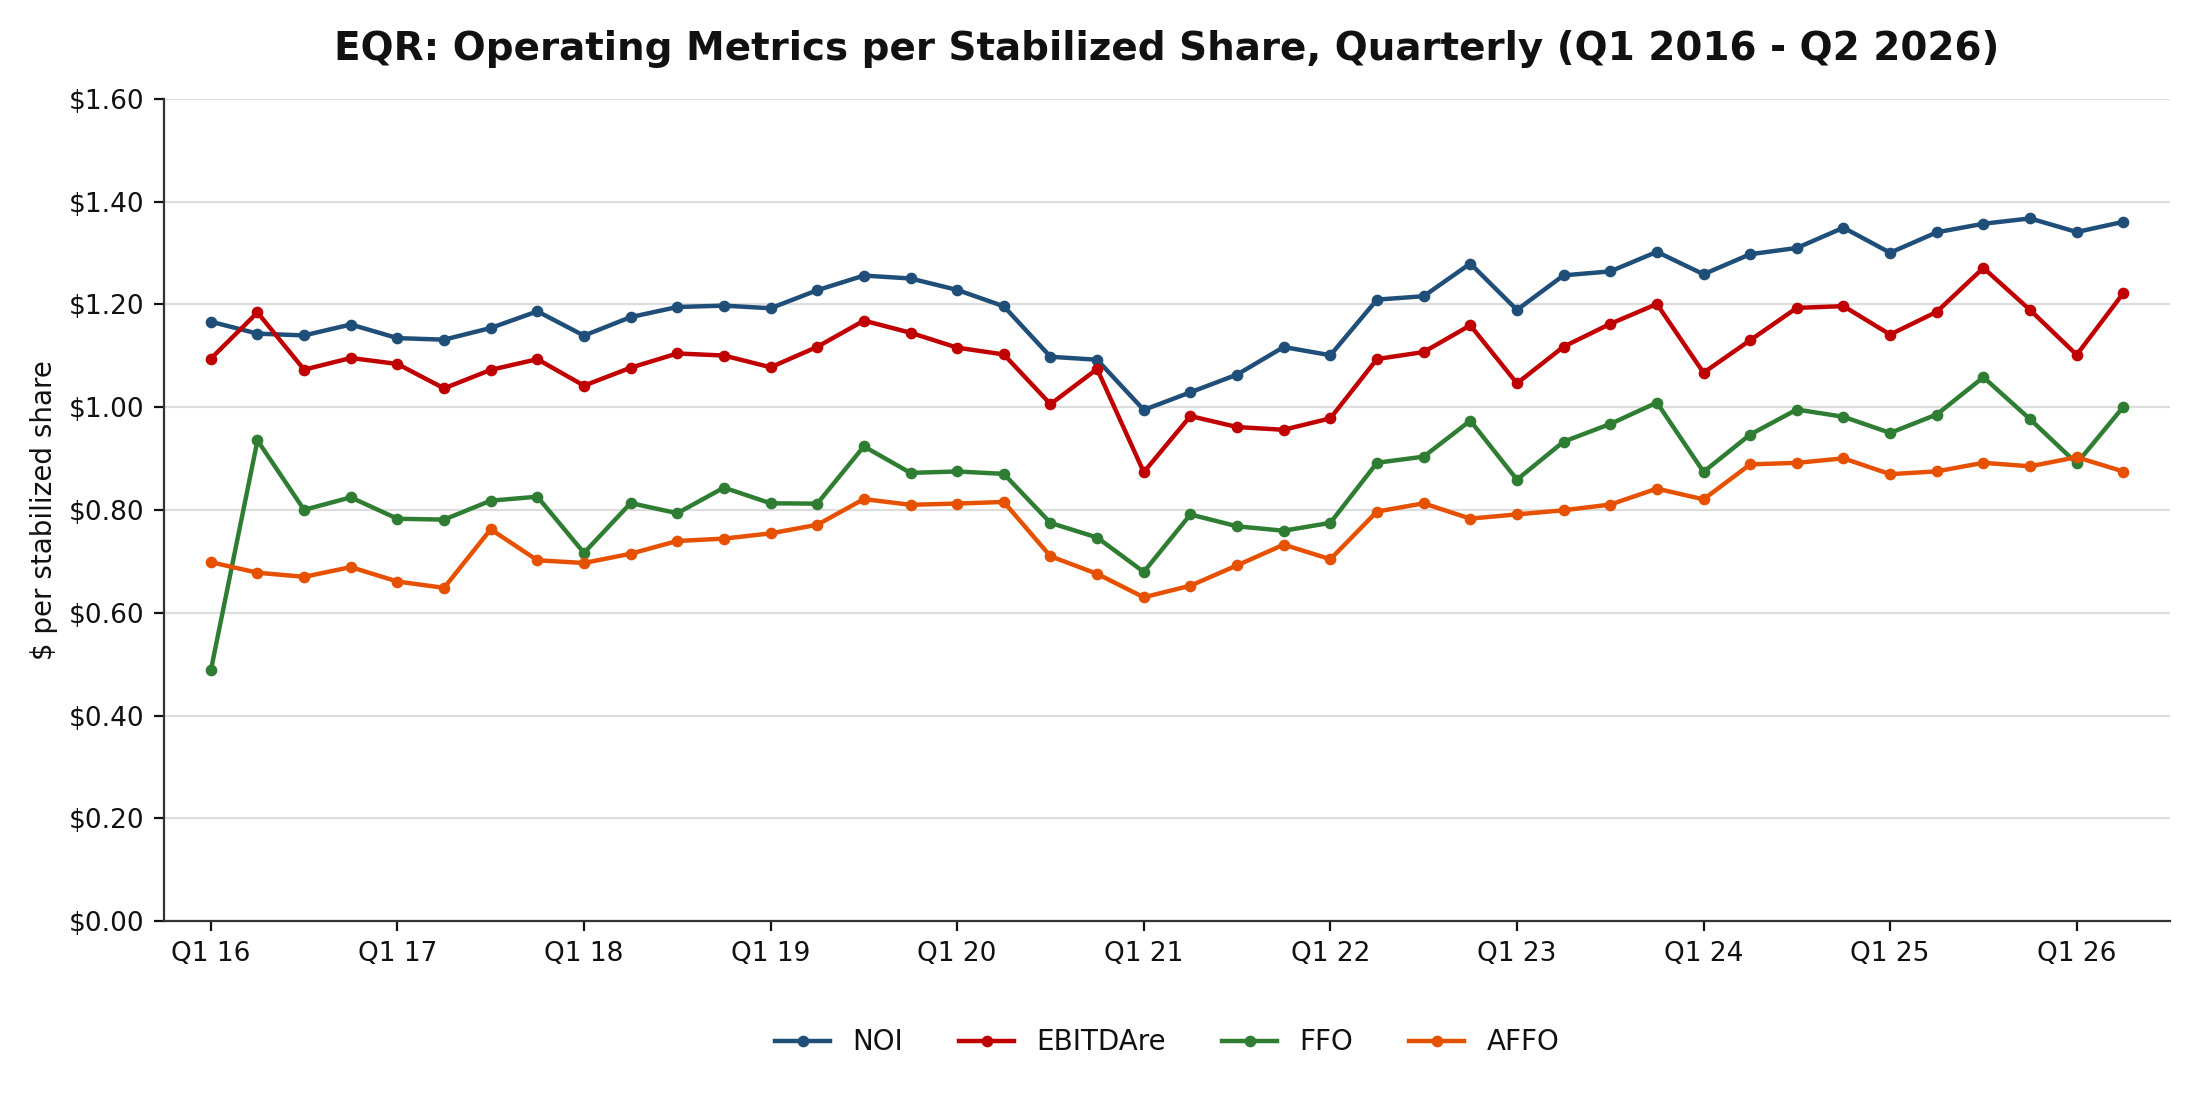
Source: Equity Residential quarterly earnings release / supplemental packages and Forms 10-Q / 10-K, Q1 2016–Q2 2026; CRE42 stabilized-share basis. Companion workbook, CHARTS STAB tab.
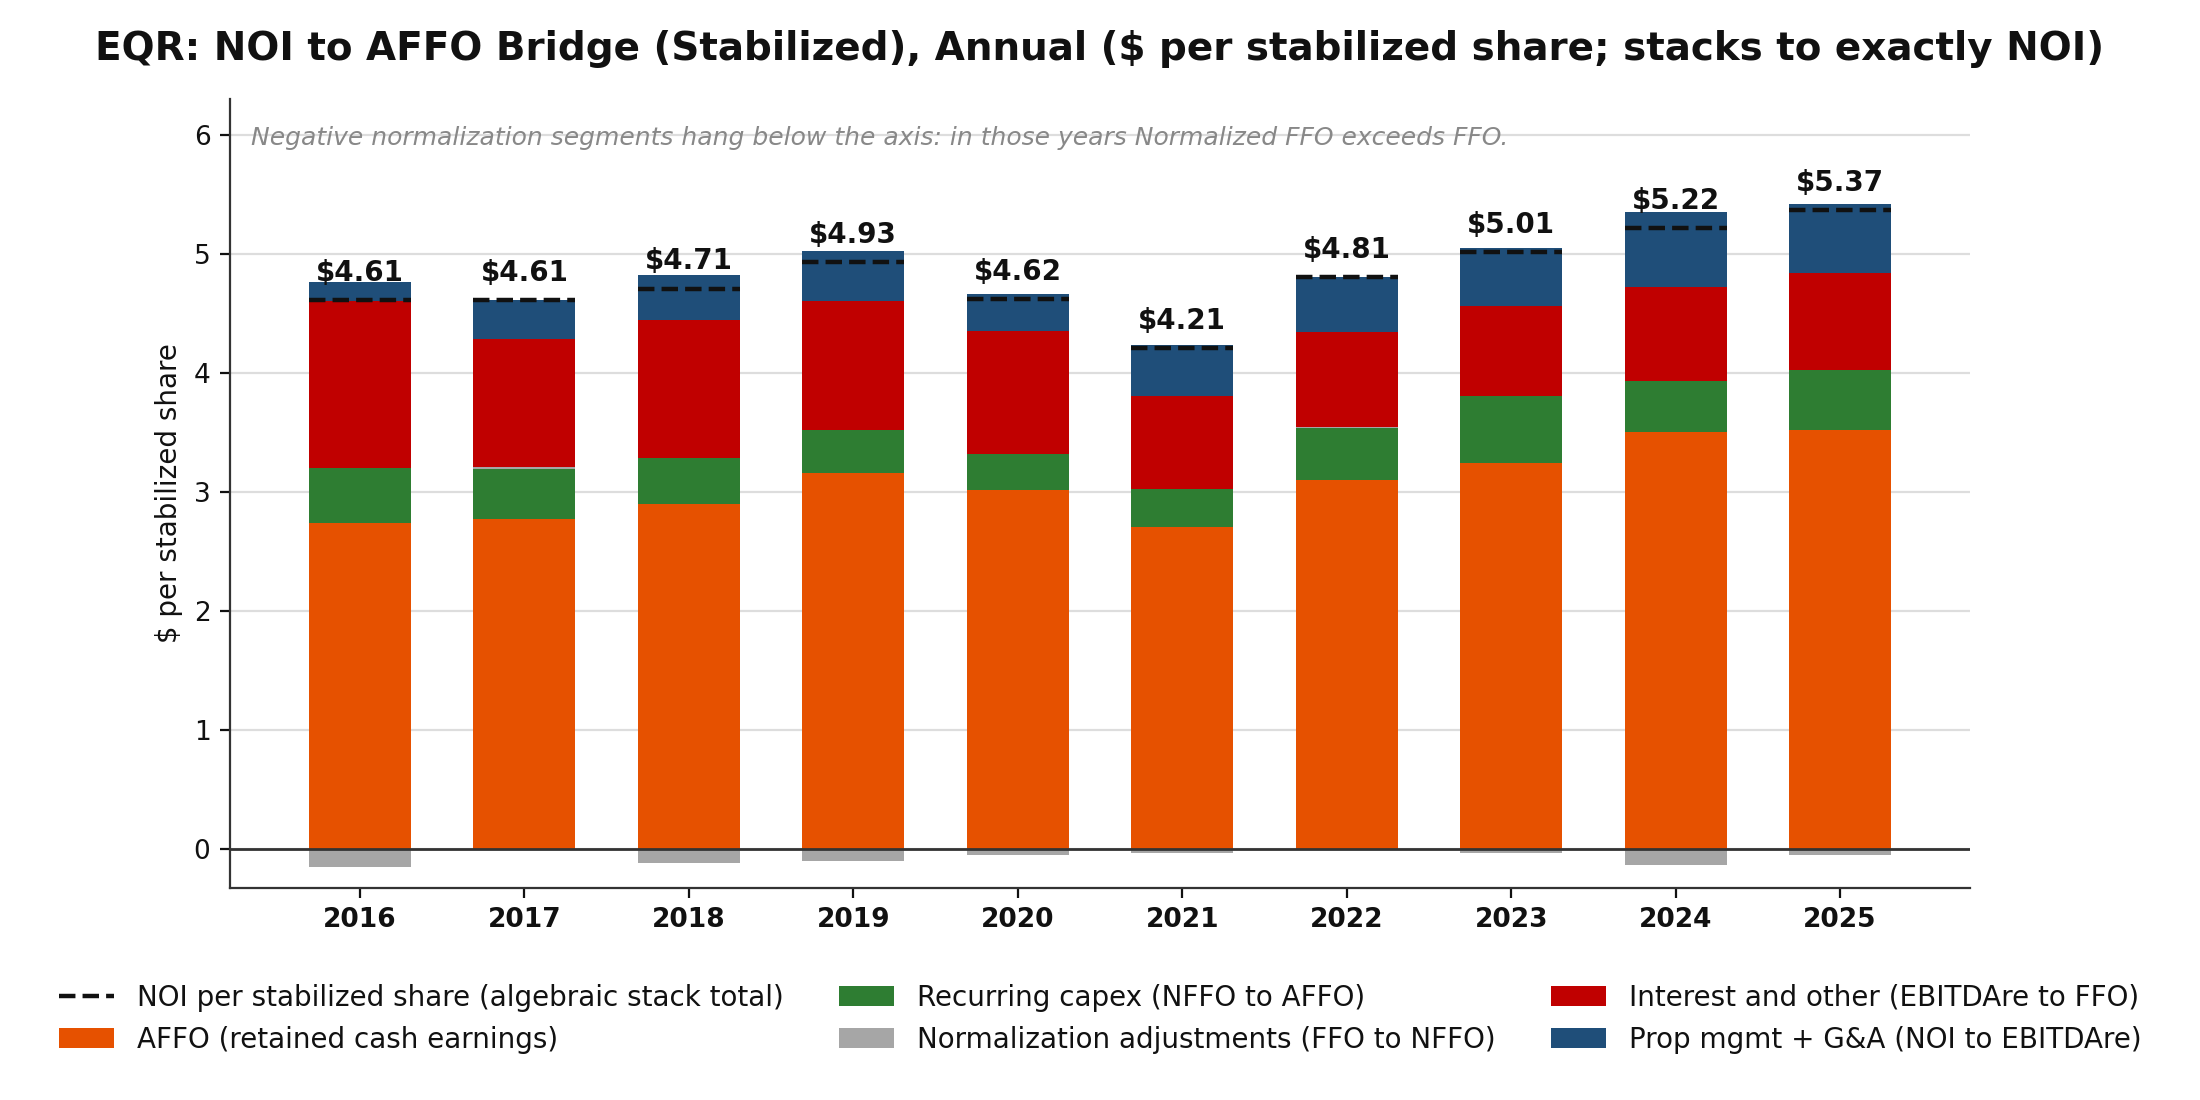
Source: Companion workbook, Quarterly Data annual block; segments are the exact differences between adjacent metrics, per stabilized share, and stack to NOI.
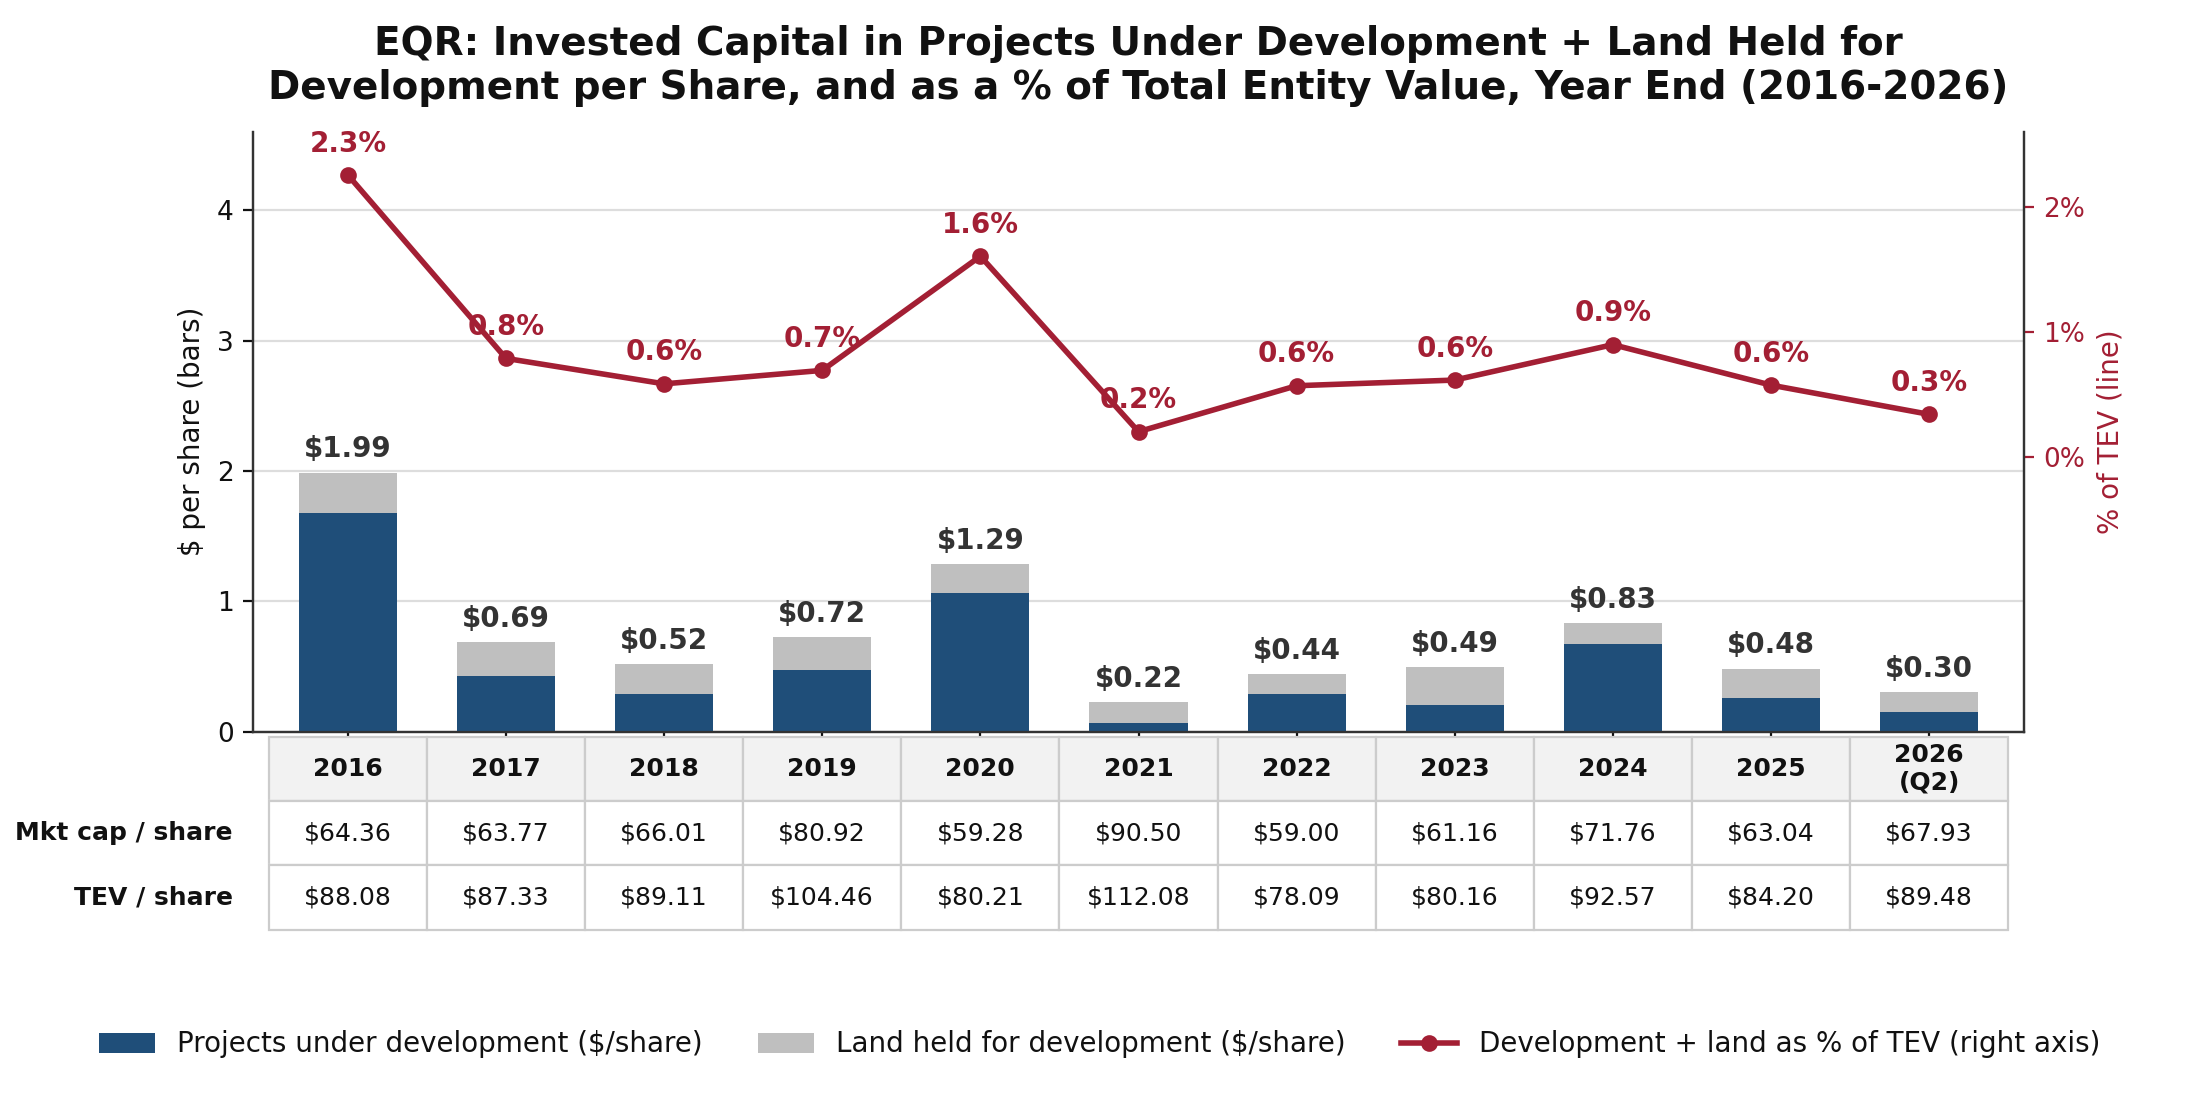
Source: Equity Residential balance sheets (supplementals and Forms 10-K / 10-Q), Q4 2016–Q2 2026; companion workbook, Quarterly Data development pipeline block (rows 169–180). Bars: "Projects under development" plus "Land held for development", per period-end share and unit; line: the same total as a percentage of TEV. 2026 = quarter end June 2026, not annualized.[3]
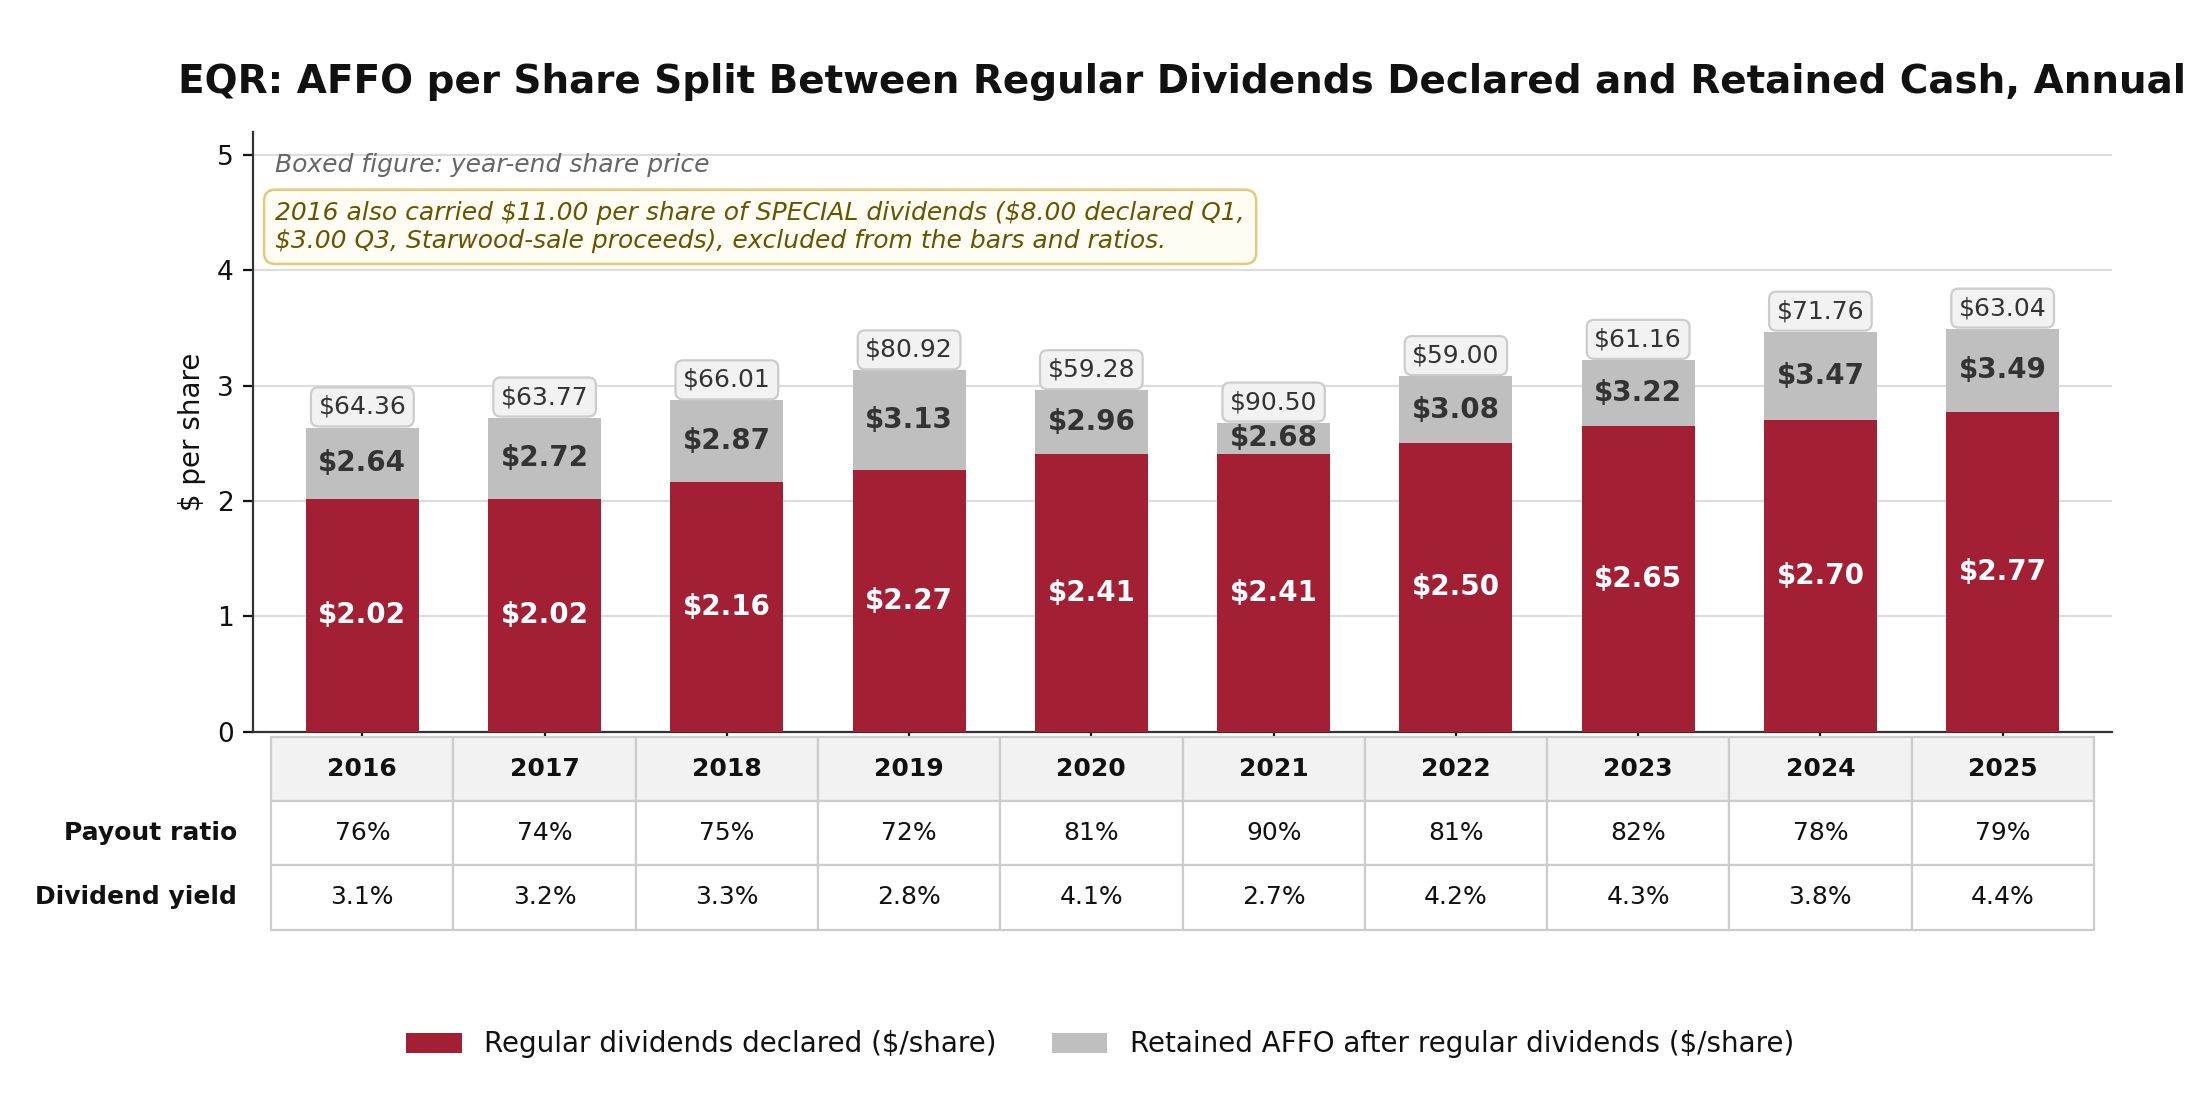
Source: Equity Residential Forms 10-K and 10-Q, 2016–2025 (dividends declared, statements of changes in equity); companion workbook, Quarterly Data dividend rows and annual block. AFFO per share on weighted-average diluted shares and units; payout ratio = regular dividends declared / AFFO; dividend yield = regular dividends declared / year-end closing price.
The chart above and the three tables below are on an as-reported basis: per-share figures use weighted-average diluted shares and units, and the yields use unadjusted market capitalization and total enterprise value. The tables higher up the page are on the stabilized basis[1], which deducts non-revenue-producing development and land from both capitalization and share counts. EQR's pipeline is small, so the two bases sit close: FY2025 AFFO reads $3.49 per share here and $3.52 per stabilized share there.
| TTM | Q3 25 | Q4 25 | Q1 26 | Q2 26 | |
|---|---|---|---|---|---|
| AFFO / MKT CAP | 5.2% | 5.5% | 5.6% | 6.1% | 5.1% |
| FFO / MKT CAP | 5.8% | 6.5% | 6.2% | 6.0% | 5.9% |
| EBITDAre / TEV | 5.4% | 5.8% | 5.6% | 5.4% | 5.4% |
| NOI / TEV | 6.1% | 6.2% | 6.4% | 6.6% | 6.1% |
| 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | 2026 ann. | |
|---|---|---|---|---|---|---|---|---|---|---|---|
| NOI | $4.44 | $4.52 | $4.67 | $4.89 | $4.53 | $4.16 | $4.78 | $4.98 | $5.16 | $5.32 | $5.37 |
| EBITDAre | $4.29 | $4.21 | $4.29 | $4.47 | $4.22 | $3.73 | $4.32 | $4.50 | $4.54 | $4.75 | $4.62 |
| FFO | $2.94 | $3.15 | $3.14 | $3.39 | $3.21 | $2.97 | $3.53 | $3.74 | $3.76 | $3.94 | $3.76 |
| AFFO | $2.64 | $2.72 | $2.87 | $3.13 | $2.96 | $2.68 | $3.08 | $3.22 | $3.47 | $3.49 | $3.54 |
| CFO | $2.91 | $3.31 | $3.54 | $3.77 | $3.28 | $3.25 | $3.73 | $3.92 | $4.03 | $4.22 | $3.65 |
| 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | 2026 ann. | |
|---|---|---|---|---|---|---|---|---|---|---|---|
| NOI | 1.7% | 3.3% | 4.7% | -7.3% | -8.2% | 15.0% | 4.2% | 3.7% | 3.1% | 1.0% | |
| EBITDAre | -1.9% | 1.9% | 4.3% | -5.6% | -11.6% | 15.7% | 4.2% | 1.0% | 4.6% | -2.7% | |
| FFO | 7.1% | -0.2% | 8.1% | -5.5% | -7.5% | 18.9% | 6.2% | 0.4% | 4.7% | -4.5% | |
| AFFO | 3.3% | 5.5% | 9.1% | -5.5% | -9.5% | 15.1% | 4.6% | 7.6% | 0.8% | 1.2% | |
| CFO | 13.7% | 6.9% | 6.7% | -13.1% | -0.9% | 15.0% | 5.0% | 2.7% | 4.8% | -13.4% |
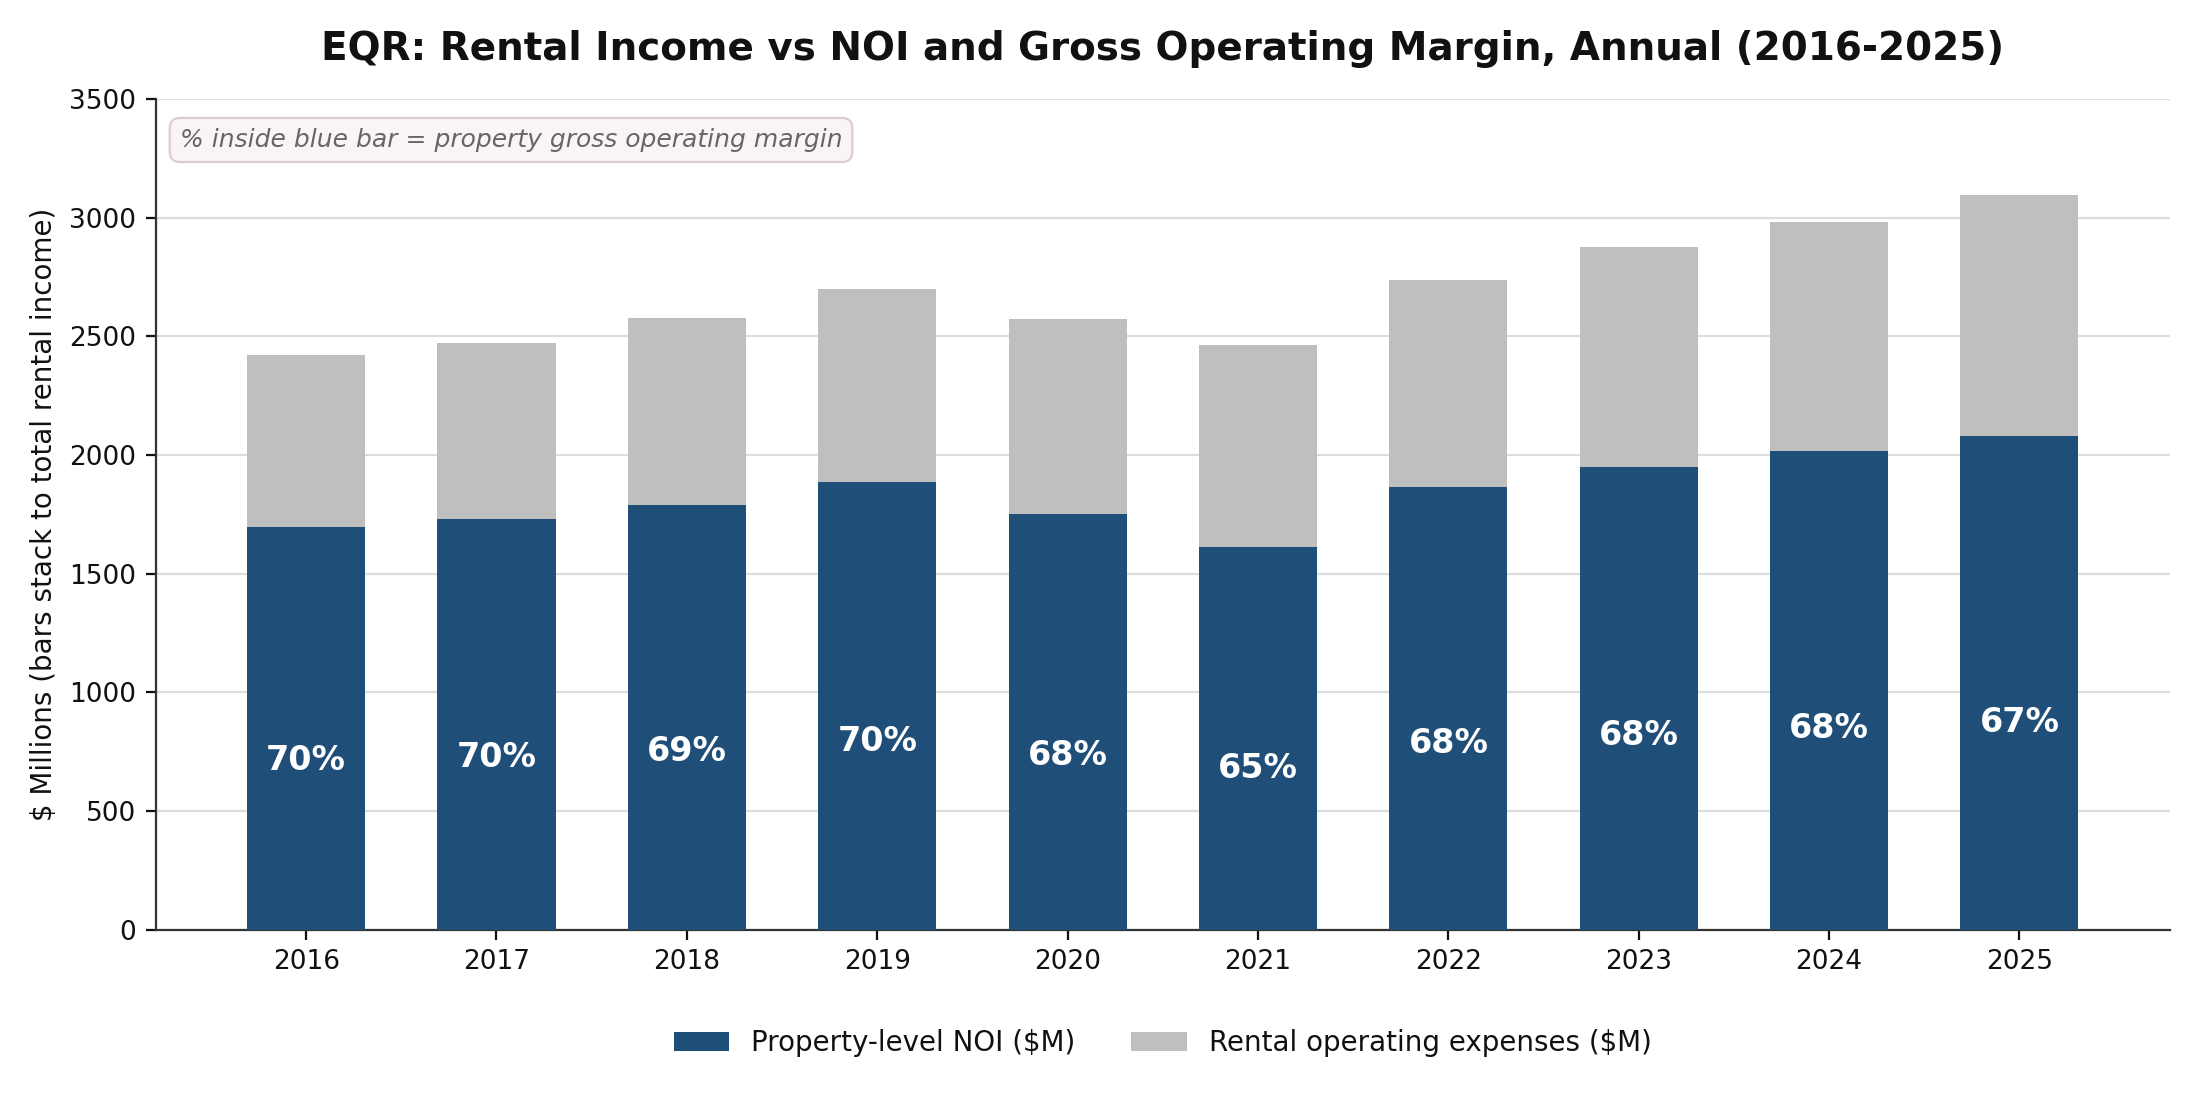
Source: Equity Residential quarterly supplementals, Additional Reconciliations section (rental income / operating expenses / NOI), full-year column, own vintage 2016–2025; cross-vintage corroborated. Margin = (total rental income less operating expenses) / total rental income. Companion workbook, Quarterly Data rows 114–118 and the detail block at rows 155–167.[4]
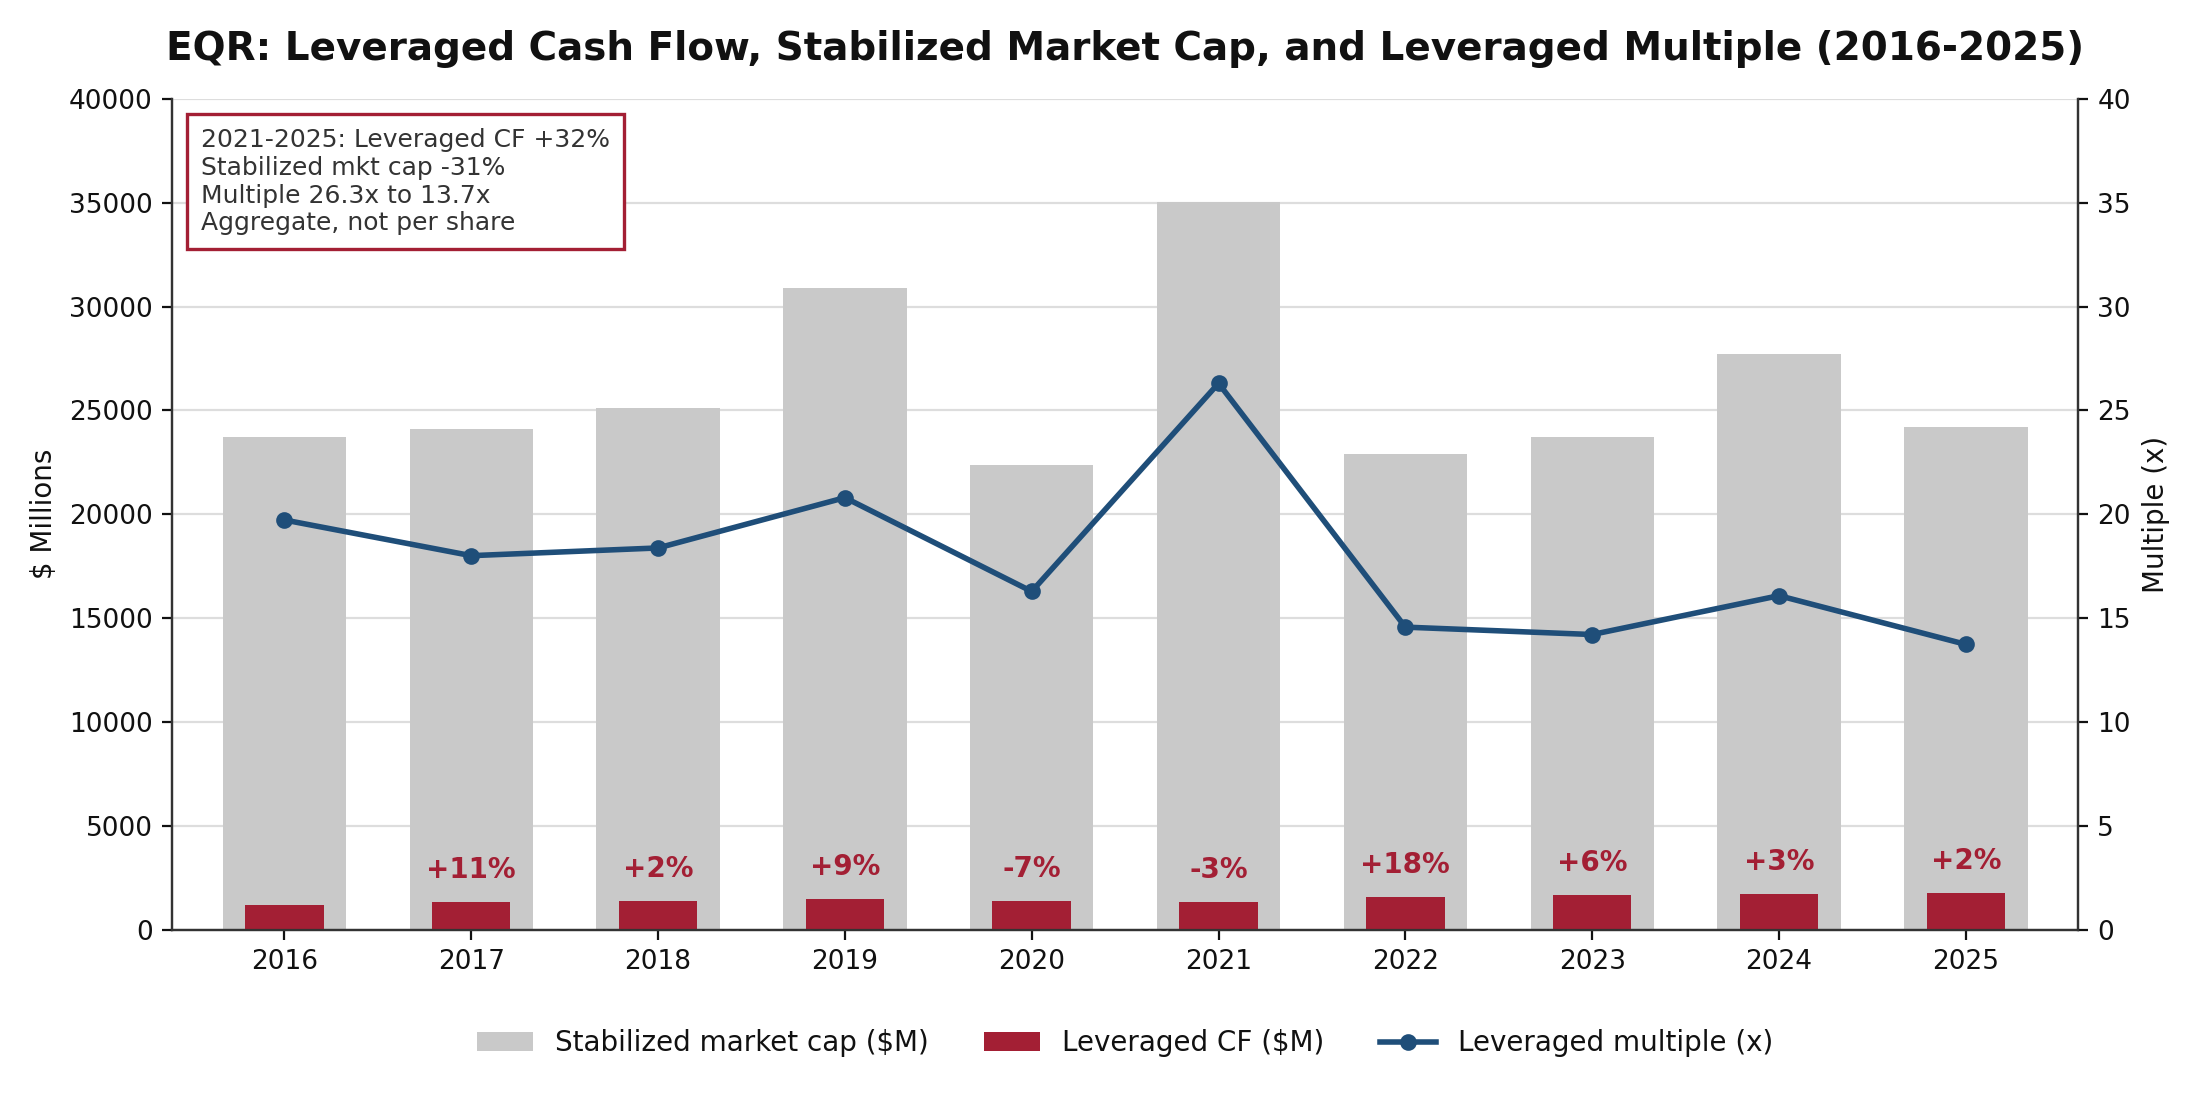
Source: Companion workbook, Quarterly Data annual block; stabilized market cap per the CRE42 method.[1] Leveraged CF = NOI less interest expense (incurred net plus amortization of deferred financing costs).
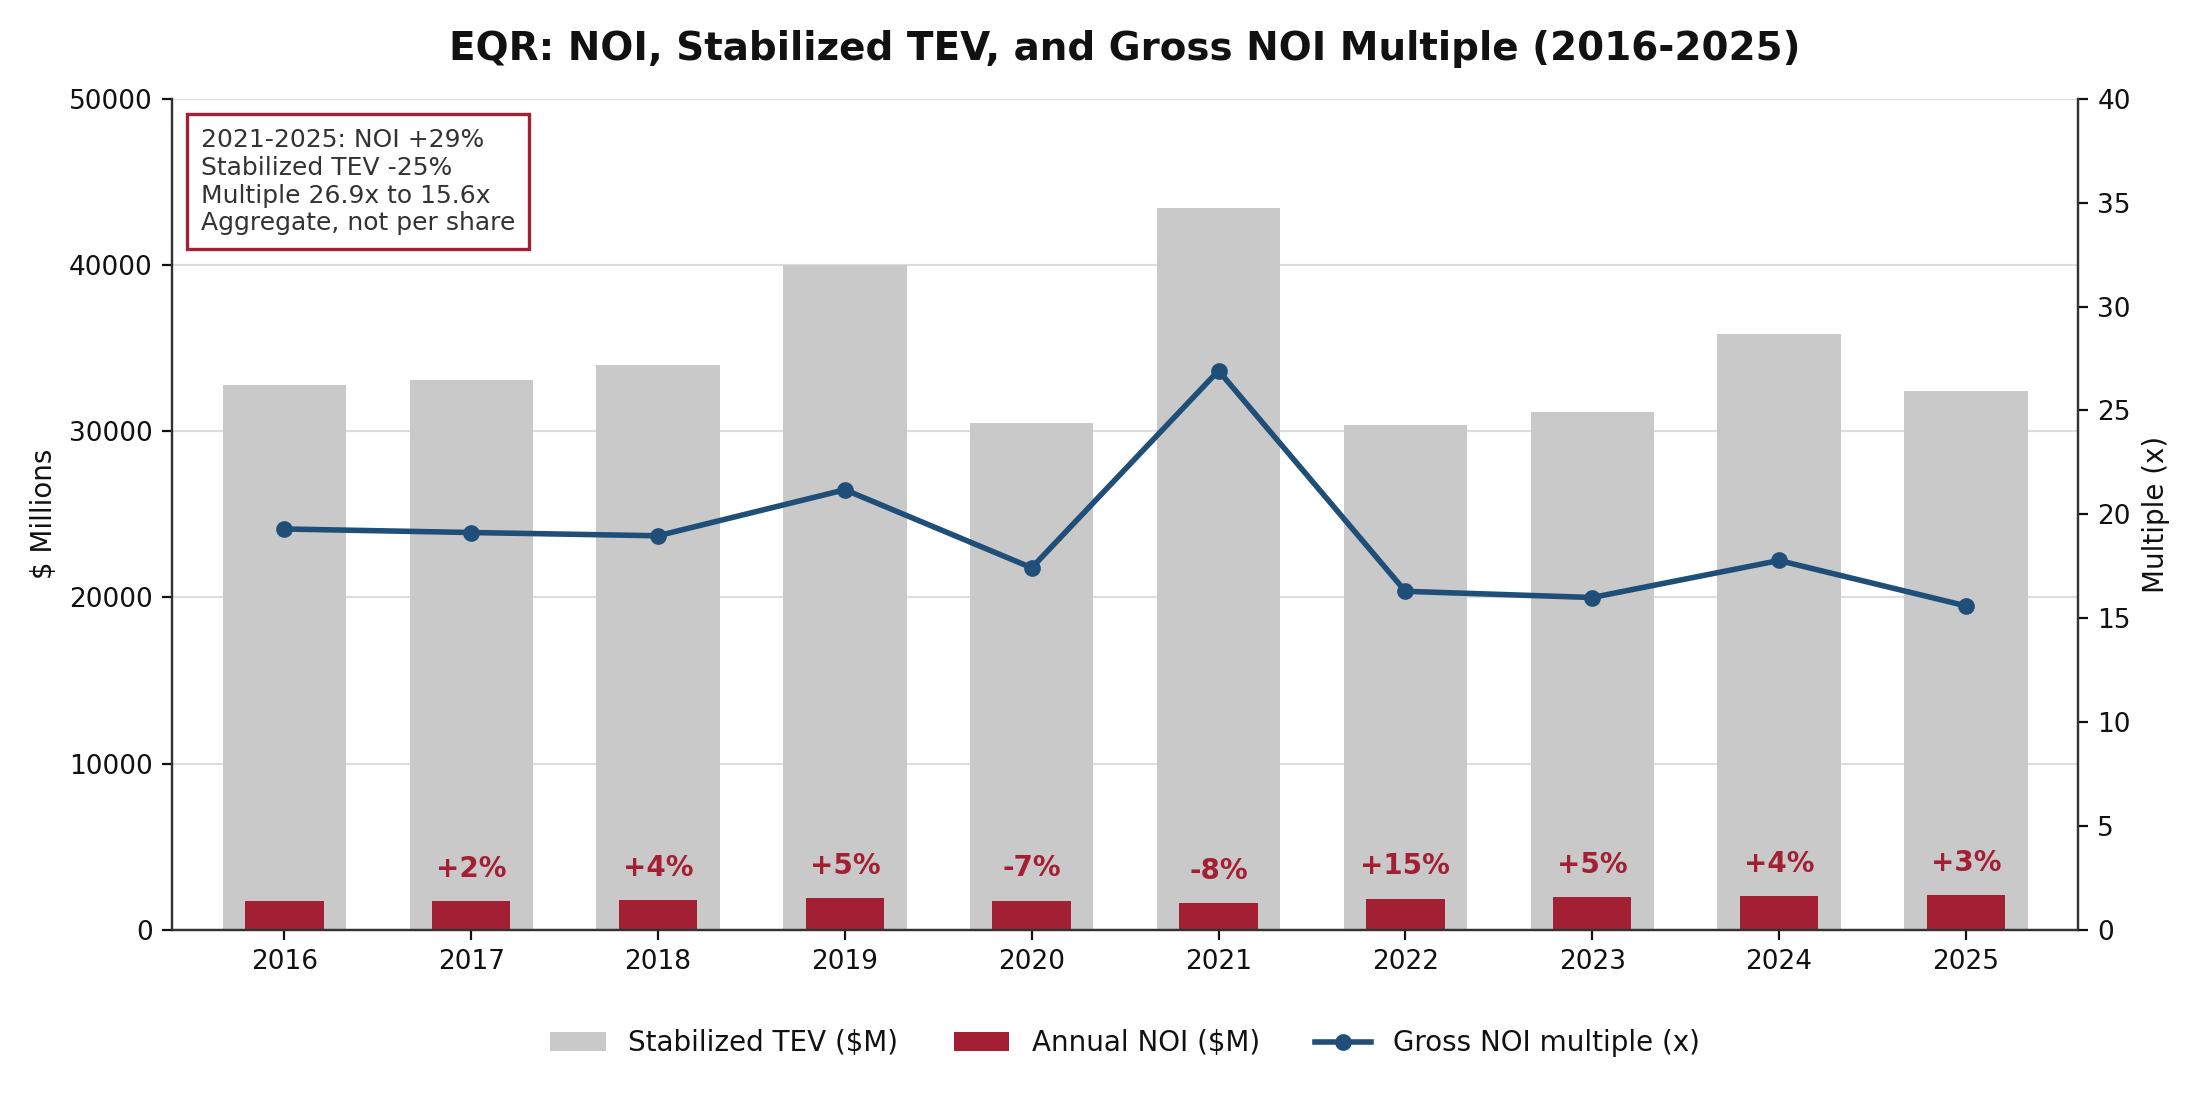
Source: Companion workbook, Quarterly Data annual block; stabilized TEV per the CRE42 method.[1]
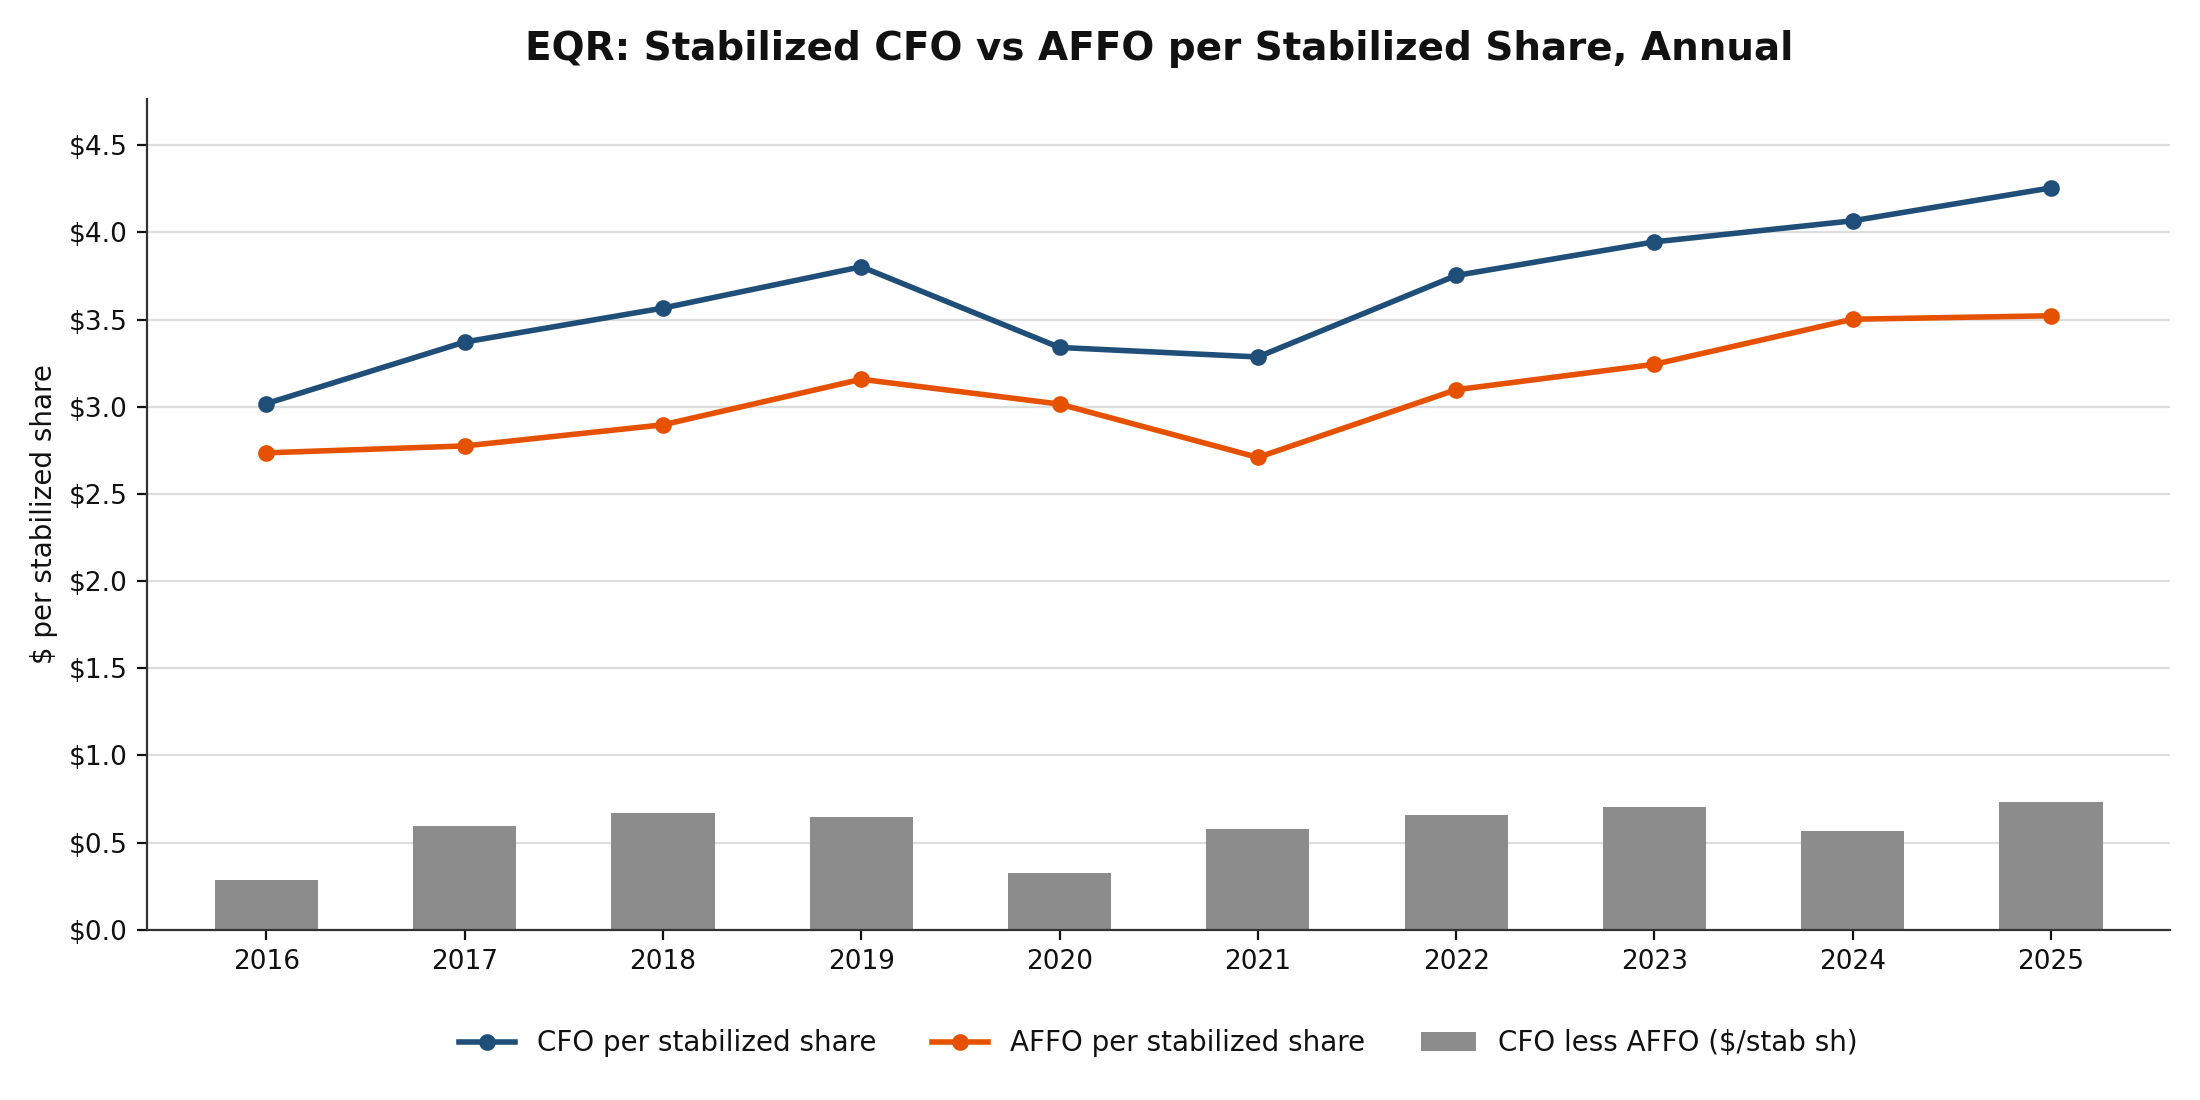
Source: Companion workbook, Quarterly Data annual block. CFO is as-reported operating cash flow; AFFO is CRE42-constructed (Normalized FFO less recurring capex).
[1] Stabilized basis, accounting mechanics. The stabilized adjustment removes from equity market capitalization and total enterprise value the cumulative invested cost of (a) consolidated apartment projects in construction or lease-up, carried on EQR's balance sheet as "Projects under development", and (b) prospective-development land held at cumulative cost, carried as "Land held for development". Per-share figures deduct the share-equivalent of the same value (dev and land value divided by the quarter-end share price) from both weighted-average diluted and period-end share-and-unit counts. Land under operating communities is not deducted; the adjustment isolates only capital that is not yet producing income. EQR moves projects out of "Projects under development" at construction completion rather than at stabilization, so the adjustment is, if anything, conservative; EQR publishes no figure to cross-check it against. Development in unconsolidated joint ventures is not on these lines and is excluded (see note [3]). Method per the CRE42 REIT-section convention; full decision trail on the companion workbook Sources tab. ↩
[2] Reading the 2026 column. Every 2026 figure on this page is the first half annualized ×2, and the series diverge that year: NOI per stabilized share rises 0.7% and AFFO rises 1.0%, while EBITDAre falls 2.9%, FFO falls 4.7% and CFO falls 13.7%. Four things drive the wedge, none of them a change in property performance. (a) Q2 2026 carries merger transaction costs ($5.1M, other expenses) and merger financing costs ($2.9M, interest expense) inside FFO and EBITDAre; Normalized FFO excludes both. (b) H1 2026 carries $50.1M of insurance and litigation reserve expense against $4.9M in H1 2025, also inside FFO and EBITDAre but outside the Normalized measures. (c) The 2025 base carries one-time income booked in Q3 2025 (a $16.9M employment-tax refund and $25.4M of unrealized investment-security gains). (d) EQR's operating cash flow is back-half weighted, so the H1 ×2 convention understates CFO in a way it does not understate NOI. AFFO reads clean in 2026 because it builds from Normalized FFO, which strips (a) and (b). EQR withdrew its EPS, FFO and Normalized FFO guidance in Q2 2026, citing the pendency of the merger with AvalonBay.
[3] Development pipeline chart. The two bar segments together equal the "dev & land value" that the stabilized adjustment in note [1] removes from market cap and TEV. Both lines are true separate balance-sheet lines every quarter (there is no AVB-style land-inside-construction overlap). What the lines do NOT capture is EQR's unconsolidated joint-venture development, which has become the larger share of its pipeline: at June 30, 2026 the supplemental's Development and Lease-Up Projects page shows $713.8M of total budgeted capital cost across all development projects, $307.2M of it in unconsolidated ventures funded partly with project-specific construction loans that are not recourse to EQR. Per-share figures divide year-end balances by period-end shares plus OP Units, the same count used for market cap and TEV per share in the table beneath the bars. The right axis is offset so the line reads clear of the bars; its zero sits mid-plot by design.
[4] Gross operating margin series. The revenue and expense lines come from the supplemental's own NOI reconciliation table (total rental income; total operating expenses), so revenue less expenses equals the published Total NOI exactly in every year: unlike the AVB margin series there is no income-statement-basis gap and no asterisk. Operating expenses include real estate taxes and insurance and exclude property management, consistent with EQR's published NOI definition in every vintage 2016–2026; the ten-year series carries no presentation break. ↩
[5] FFO endpoint CAGR. The stabilized CAGR table uses single-quarter endpoints (Q1 2016 to Q2 2026). Q1 2016 FFO of $178.5M carries the debt-extinguishment and prepayment costs of the deleveraging that followed the Starwood portfolio sale, so the FFO row's CAGR is inflated by a depressed base quarter. Normalized FFO excludes those costs; the AFFO row (built from Normalized FFO) is unaffected.
Data. Equity Residential quarterly earnings release / supplemental packages and Forms 10-K / 10-Q, Q1 2016 through Q2 2026. Unlike AVB, EQR publishes quarter-end share prices, share and unit counts, market capitalization and preferred equity on the supplemental's Capital Structure page, so built market cap and TEV tie to published figures in all 42 quarters. EQR publishes no AFFO, so the AFFO series here is a CRE42 construct (Normalized FFO less recurring capex) with no published figure to tie to; recurring capex is Building Improvements plus Replacements through Q1 2024 and EQR's published Recurring Capital Expenditures line from Q2 2024, when that disclosure began (2016 and H1 2017 include renovation spend inside Replacements, flagged on the workbook Sources tab). All derived figures tie to published totals in the companion workbook; every input is cited on its Sources tab. Trailing yields and multiples use trailing-twelve-month results against quarter-end June 2026 stabilized capitalization. On May 21, 2026 EQR and AvalonBay announced an all-stock merger of equals expected to close in H2 2026; this page is Equity Residential's standalone pre-merger record.
Companion workbook. EQR-individual-metrics.xlsx – 42-quarter per-share grid (as reported and stabilized), derivations tied to published figures, annual aggregations, and native chart tabs (CHARTS, CHARTS STAB).